The Issuance of RMC 97-2026
Last September 14, 2026, the BIR issued Revenue Memorandum Circular (RMC) No. 97-2026, formally aligning with the position of the Energy Regulatory Commission (ERC) under ERC Resolution No. 26-2026—making the “allowable system loss charge” on electricity bills (subject to the ERC-approved cap) to be treated as a government-mandated pass-through cost and not be considered as income of power entities.
As a result, the system loss charge is now:
- Excluded from gross sales of generation companies, National Grid Corporation of the Philippines, and distribution utilities (including electric cooperatives) for VAT purposes
- No longer subject to 12% output VAT
- No longer subject to creditable withholding tax on VAT (CWT-VAT)
Notably, this builds up on RMC 60-2026, which earlier clarified the VAT treatment of the Lifeline Subsidy and Green Energy Auction Allowance.
What is the "System Loss Charge," and Why Does it have a Cap?
The system loss charges refer to the electricity lost while going through the transmission and distribution system because of both technical factors, such as heat in wires or transformers, and non-technical factors, such as theft or illegal connections. Under the Republic Act 9136 or the Electric Power Industry Reform Act, power companies are allowed to recover a portion of this from the consumers, but the ERC sets a cap on how much can be passed on:
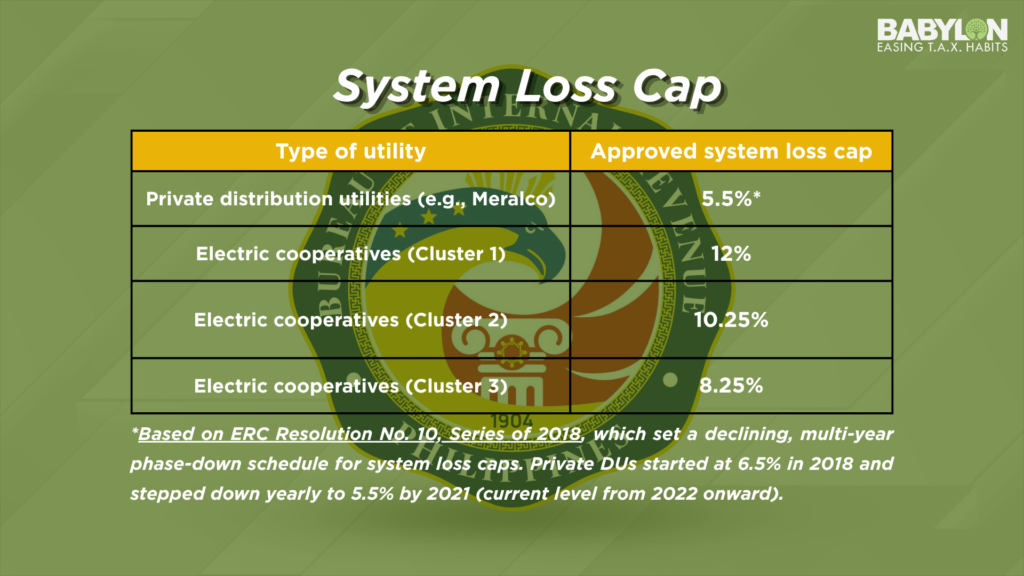
More importantly, if a utility exceeds its prescribed cap, such as due to power theft or weak infrastructure, such excess loss cannot be passed to consumers. Thus, VAT relief applies only within the cap.
How much can you actually save?
For a better view of the benefits, here is an example of how much you can save per bill:
- For a typical Meralco bill, the system loss charge is roughly 5% of the total bill
- If your monthly electric bill is, for example, amounting to ₱10,000, the system loss portion is around ₱500
- The old 12% VAT on that portion would be about ₱60, and that’s your monthly savings, making a ₱720 savings on a yearly basis.
Moreover, it depends entirely on how much a business consumes, so higher consumption means more savings. For example:
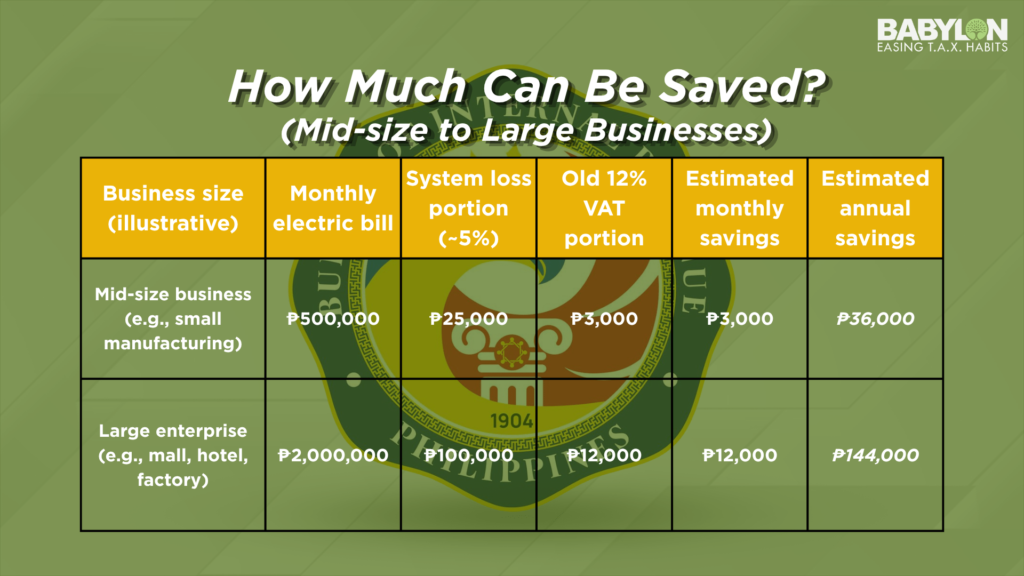
However, keep in mind this is not a refund, as it has no retroactive effect on past bills. The change is prospective only and applies to electric bills from the effective date of the RMC and ERC Resolution onward.
What is not affected?
- Only VAT was removed, making income tax and its corresponding withholding taxes remain unaffected
- The system loss charge itself is not yet abolished; you will still pay it, just without the VAT
- Distribution utilities must separately show the allowable system loss charge on billing statements. Hence, it is worth checking your next bill to verify the computation
Need help verifying your electric bill computation, or have other tax compliance concerns? Babylon2k is ready to help. Just send us a message